McLaren Insurance Cost
Across 18 McLaren models, full coverage averages about $1,765 a year by our estimate — +11% versus the average vehicle ($1,590).
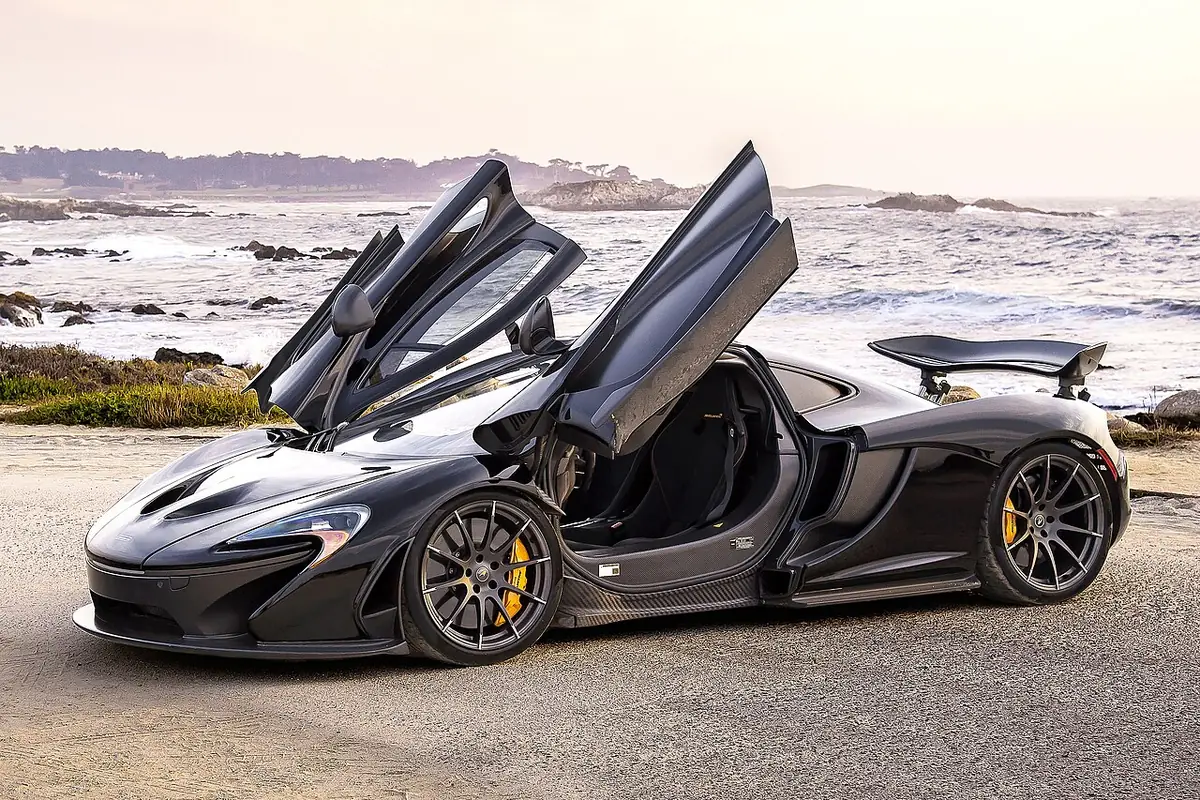
McLaren insurance profile
McLaren is a luxury brand, so repair parts, sensors and labor tend to cost more. Its current lineup includes 18 luxury sports cars.
Every McLaren model ranked by insurance cost
| Model | Segment | Model years | HLDI collision | Est. full / yr | vs. avg car |
|---|---|---|---|---|---|
| P1 | Luxury sports car | 2014–2015 | — | $1,580 | −1% |
| MP4-12C | Luxury sports car | 2012–2014 | — | $1,580 | −1% |
| 675LT | Luxury sports car | 2016–2016 | — | $1,585 | 0% |
| MSO HS | Luxury sports car | 2016–2016 | — | $1,585 | 0% |
| 650S | Luxury sports car | 2015–2016 | — | $1,585 | 0% |
| 540C | Luxury sports car | 2018–2018 | — | $1,700 | +7% |
| Senna | Luxury sports car | 2019–2019 | — | $1,755 | +10% |
| 570GT | Luxury sports car | 2017–2019 | — | $1,755 | +10% |
| 620R | Luxury sports car | 2020–2020 | — | $1,810 | +14% |
| Sabre | Luxury sports car | 2020–2020 | — | $1,810 | +14% |
| Speedtail | Luxury sports car | 2020–2020 | — | $1,810 | +14% |
| 600LT | Luxury sports car | 2019–2020 | — | $1,810 | +14% |
| 570S | Luxury sports car | 2016–2020 | — | $1,810 | +14% |
| Elva | Luxury sports car | 2021–2021 | — | $1,865 | +17% |
| 765LT | Luxury sports car | 2021–2022 | — | $1,920 | +21% |
| GT | Luxury sports car | 2020–2022 | — | $1,920 | +21% |
| 720S | Luxury sports car | 2018–2022 | — | $1,920 | +21% |
| Artura | Luxury sports car | 2023–2023 | — | $1,975 | +24% |
What makes McLaren insurance cost more or less
- Luxury parts and labor: premium materials, advanced driver-assistance sensors and dealer-only repairs raise collision claim costs.
- Segment mix: 18 luxury sports car.
Average McLaren insurance cost by state
Average full-coverage estimate across current McLaren models, cheapest state first.
| State | Avg. full coverage | vs. national |
|---|---|---|
| Maine | $1,440 | −18% |
| Idaho | $1,510 | −14% |
| Vermont | $1,515 | −14% |
| North Dakota | $1,520 | −14% |
| Wisconsin | $1,545 | −12% |
| Hawaii | $1,565 | −11% |
| Iowa | $1,580 | −10% |
| Indiana | $1,595 | −10% |
| New Hampshire | $1,605 | −9% |
| Ohio | $1,610 | −9% |
| North Carolina | $1,735 | −2% |
| South Dakota | $1,815 | +3% |
| Kansas | $1,835 | +4% |
| Kentucky | $1,835 | +4% |
| Montana | $1,840 | +4% |
| Nebraska | $1,840 | +4% |
| Wyoming | $1,855 | +5% |
| Washington | $1,860 | +5% |
| Minnesota | $1,890 | +7% |
| Tennessee | $1,890 | +7% |
| Oregon | $1,895 | +7% |
| Virginia | $1,900 | +8% |
| West Virginia | $1,910 | +8% |
| Utah | $1,930 | +9% |
| Illinois | $1,945 | +10% |
| Alaska | $1,950 | +10% |
| Alabama | $1,975 | +12% |
| Pennsylvania | $1,985 | +12% |
| New Mexico | $2,000 | +13% |
| Arkansas | $2,030 | +15% |
| Missouri | $2,035 | +15% |
| Oklahoma | $2,055 | +16% |
| Mississippi | $2,155 | +22% |
| Massachusetts | $2,180 | +23% |
| California | $2,225 | +26% |
| South Carolina | $2,265 | +28% |
| Connecticut | $2,280 | +29% |
| Arizona | $2,285 | +29% |
| Delaware | $2,335 | +32% |
| Nevada | $2,360 | +34% |
| Maryland | $2,435 | +38% |
| Michigan | $2,435 | +38% |
| Colorado | $2,525 | +43% |
| New Jersey | $2,525 | +43% |
| Rhode Island | $2,580 | +46% |
| Georgia | $2,605 | +48% |
| Texas | $2,660 | +51% |
| District of Columbia | $2,810 | +59% |
| New York | $2,840 | +61% |
| Florida | $2,925 | +66% |
| Louisiana | $3,005 | +70% |
Frequently asked questions
How much does it cost to insure a McLaren?
Across 18 current McLaren models, our full-coverage estimate averages $1,765 a year for a driver in their 30s with a clean record, 11% more than the average vehicle ($1,590).
What is the cheapest McLaren to insure?
The McLaren P1 has the lowest estimate at about $1,580 a year for full coverage; the McLaren Artura is the most expensive at about $1,975.
Where is it cheapest to insure a McLaren?
By our estimates, Maine is the cheapest state (about $1,440 a year on average across current models) and Louisiana the most expensive (about $3,005).
How we estimate this
We start from the state's average liability, collision and comprehensive premiums published by the NAIC, then apply a location factor (population density and commute time from the Census ACS, weather hazard scores from FEMA's National Risk Index), a vehicle factor (HLDI insurance-loss data where available, otherwise vehicle segment), and a driver-profile multiplier. Results are rounded ranges for comparison, not quotes. Read the full methodology.